Healthy at 65+? Medicare Advantage vs. Medigap for Active Adults
Medicare Advantage vs Medigap 2027 for Healthy Adults
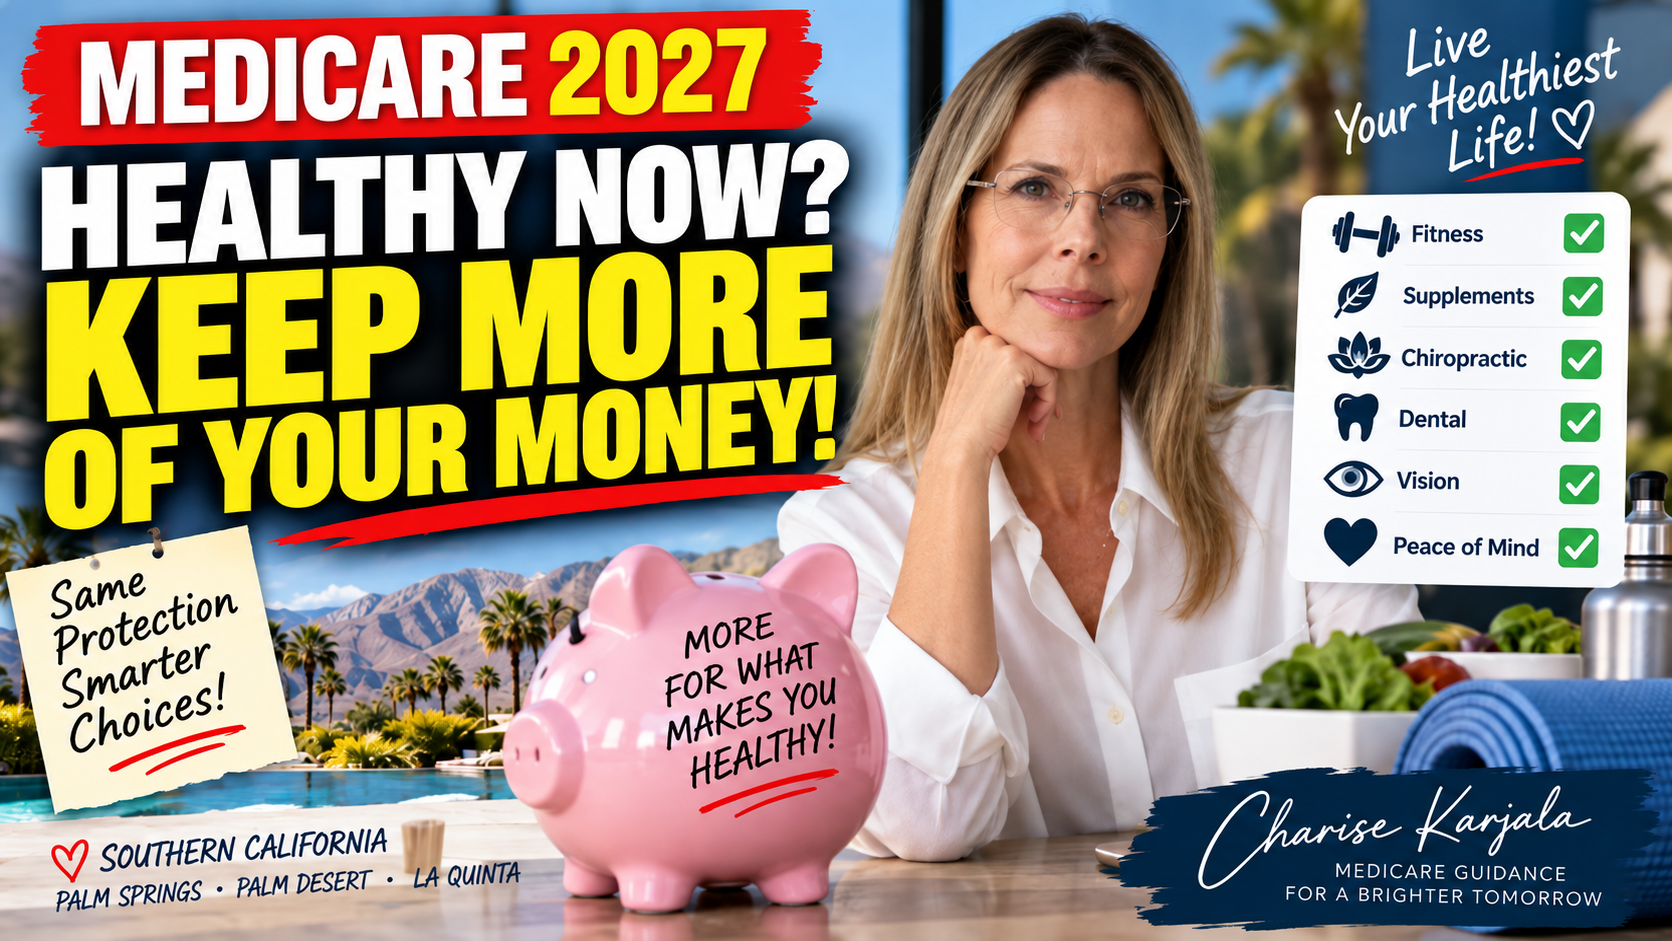
If you're turning 65, or you're already on Medicare and consider yourself relatively healthy, you may find yourself asking a very different question from many other Medicare beneficiaries:
What am I actually paying for?
Maybe you don't see specialists every month.
Maybe you rarely go to the doctor.
Maybe you spend more money on staying healthy than you do on treating illness.
That could include things like:
- Pilates
- Personal training
- Chiropractic care
- Acupuncture
- Dental care
- Vision care
- Supplements
- Concierge medicine
- Other wellness services
That is exactly the kind of person I was talking about in my second Medicare video.
For someone like that, the Medicare conversation can become much more interesting.
Not because one type of coverage is automatically better than another.
But because the value of coverage depends heavily on how you actually use healthcare.
The First Question: What Are You Paying for Every Month?
Let's say you're spending money on your health already.
Perhaps you're paying:
- $200 a month for Pilates or personal training
- $300 a month on supplements
- $400 a month on dental and vision
- Additional money on chiropractic care
- Additional money on a concierge physician
And then, on top of that, you're paying a monthly premium for Medigap.
At some point, it's fair to ask:
Is this still the best allocation of my healthcare dollars?
That doesn't mean you should cancel Medigap.
It means you should review the entire picture.
In the transcript, Charise frames this around people who are already spending significant amounts on their own health and wellness while also paying for a Medigap policy they may rarely use.
That is a legitimate financial question.
What Medigap Is Really Buying You
One of the major advantages of Medigap is access.
Charise describes Medigap as particularly valuable for people who want the flexibility to seek multiple opinions or consult high-level specialists and medical institutions.
That matters.
If you want the ability to see specialists around the country, or if you're managing a complicated medical situation where access to multiple experts is important, that flexibility may be extremely valuable to you.
But if you are otherwise healthy and rarely use that access, the question becomes:
How much is that flexibility worth to you today?
For some people, the answer is: a lot.
For others, maybe not as much.
That is where a Medicare review becomes useful.
Medicare Advantage May Appeal to Healthy, Active Adults for Different Reasons
Medicare Advantage plans can be attractive to some healthy beneficiaries because they may include additional benefits beyond Original Medicare.
Depending on the specific plan, those may include things such as:
- Dental
- Vision
- Hearing
- Fitness
- Over-the-counter allowances
- Transportation
- Wellness-related benefits
Charise's point in the video is that some Medicare Advantage plans may provide benefits that align with expenses certain healthy adults are already paying for on their own.
That is where the comparison gets interesting.
Instead of only asking:
"Which plan has the lowest premium?"
Ask:
"Which structure gives me the best overall value for the way I actually live?"
That is a much better question.
But Don't Make the Mistake of Looking Only at Today's Health
This is where healthy people can sometimes get too confident.
You may feel great today.
You may exercise regularly.
You may eat well.
You may rarely see a doctor.
That is all good.
But Medicare coverage isn't just about today.
You also have to think about:
- What happens if you need surgery?
- What happens if you develop cancer?
- What happens if you have a cardiac event?
- What happens if you suddenly need multiple specialists?
- What happens if you want a second or third opinion?
Charise acknowledges this directly in the transcript by contrasting healthy adults' current spending habits with the value of broader access when serious medical needs arise.
So while your current health matters, your future risk tolerance matters too.
Think About Medicare as a Tradeoff
This is the simplest way I know to explain the Medicare Advantage vs. Medigap decision for healthy adults:
Medigap can provide broader access and predictability.
Medicare Advantage may offer lower premiums and additional benefits, but often within a more structured network and plan system.
Neither sentence means one is better.
It means they solve different problems.
A healthy person who strongly values freedom of access may still prefer Medigap.
A healthy person who rarely uses medical care and values lower monthly costs or additional benefits may decide Medicare Advantage deserves serious consideration.
That is the kind of discernment Charise is encouraging throughout the video.
What About a Hybrid Approach?
One of the more interesting ideas in Charise's transcript is what she calls a kind of hybrid approach.
The basic idea is:
Use Medicare coverage for major healthcare protection, while continuing to self-fund the wellness services you value most.
That could mean keeping money available for:
- Concierge medicine
- Fitness
- Pilates
- Supplements
- Chiropractic care
- Other personal wellness expenses
Charise specifically describes this as a possible strategy for someone who wants to combine Medicare Advantage coverage with self-funded wellness or concierge care.
That won't be right for everyone.
But for some healthy adults, it may be worth discussing.
Healthy at 65+? Ask Yourself These Questions
Before choosing between Medicare Advantage and Medigap, I would work through this list.
How often do I actually use traditional medical care?
Do you see multiple specialists?
Or do you mostly use healthcare for preventive visits and occasional needs?
How important is broad provider access to me?
Would you want the freedom to seek care from major medical systems or specialists outside your immediate area?
How much am I spending on wellness already?
Look at the total.
Not just Medicare premiums.
Include:
- Dental
- Vision
- Fitness
- Chiropractic
- Concierge care
- Supplements
- Other wellness expenses
Would Medicare Advantage benefits replace expenses I'm already paying?
Don't assume they will.
Review the actual plan.
But if they do, that can affect the financial comparison.
What would happen if my health changed suddenly?
This may be the most important question.
Could you live comfortably with the network and rules of the plan you are considering?
How much financial risk am I comfortable accepting?
Lower premiums can be attractive.
But they should always be evaluated alongside:
- Copays
- Coinsurance
- Maximum out-of-pocket costs
- Provider access
- Referral requirements
- Prior authorization
Don't Compare Plans Only by Premium
This deserves its own section because it's one of the easiest mistakes to make.
A $0 or low-premium Medicare Advantage plan can look extremely attractive.
But that does not mean it is free healthcare.
You still need to understand:
- Copays
- Coinsurance
- Maximum out-of-pocket limits
- Drug costs
- Provider networks
- Hospital access
- Prior authorization
- Referrals
Similarly, a Medigap premium may look expensive until you consider the access and predictability it can provide.
The real question isn't:
"Which one costs less every month?"
It's:
"Which one gives me the best combination of access, protection, benefits, and financial predictability for the way I live?"
Active Adults Often Have Different Priorities
One of the reasons this topic is important in Southern California is that many Medicare beneficiaries here are extremely active.
People are:
- Golfing
- Playing pickleball
- Hiking
- Doing Pilates
- Working with trainers
- Traveling
- Using concierge medicine
- Spending money proactively on health
Those people may have very different priorities from someone managing several serious chronic illnesses.
And that is exactly why Medicare should not be treated like a one-size-fits-all product.
Your Medicare Coverage Should Match Your Lifestyle
There is no prize for having the most expensive coverage.
There is also no prize for finding the cheapest plan.
The goal is to find coverage that fits:
Your health.
Your lifestyle.
Your doctors.
Your financial situation.
Your tolerance for risk.
And:
The way you actually use healthcare.
That is the heart of Charise's message in this video.
Watch: Medicare Advantage vs. Medigap for Healthy Adults
In this video, Charise explains why healthy adults who already invest heavily in wellness may want to think differently about Medicare coverage and the role that benefits, premiums, and access play in the decision.
Need Help Deciding Between Medicare Advantage and Medigap?
If you're healthy, active, and unsure whether you're paying for more coverage than you need—or worried about giving up access you may value later—a Medicare review can help clarify the tradeoffs.
If you're in Palm Springs, Palm Desert, La Quinta, Rancho Mirage, or elsewhere in Southern California, Charise Karjala can help you review your current situation and the options available to you.
Schedule a 15-Minute Medicare Conversation With Charise
We'll look at:
- Your current coverage
- Your doctors
- Your wellness spending
- Your healthcare priorities
- Your financial comfort level
- Your expected healthcare needs
Then you can make a decision based on your life—not somebody else's.
Continue the 2027 Medicare Guide
← Medicare Advantage 2027: Will You Still Be Able to See Your Doctors?
← Complete 2027 Medicare Guide
Next → 3 Reasons to Consider Medigap in 2027
Medicare plan benefits, provider networks, costs, eligibility, underwriting rules, and additional benefits vary by plan and location. Always review official plan information and your individual circumstances before enrolling or changing coverage.