Medicare 2027 Guide for Southern California: 4 Decisions to Review Before Open Enrollment
Medicare 2027 Guide: Medicare Advantage vs Medigap in California
Medicare 2027: Four Decisions Worth Reviewing Before You Choose Your Coverage.
If you’re approaching Medicare enrollment for 2027, you’re probably going to hear a lot about premiums, benefits, networks, dental coverage, vision benefits, prescription drugs, and additional perks.
Those things matter.
But after working with Medicare beneficiaries for years, I think there is a better place to start:
- How do you actually use healthcare?
- Are you managing several chronic conditions?
- Are you healthy and rarely see a doctor?
- Do you want the freedom to see specialists around the country?
- Have you become frustrated with your current provider network?
- Has your Medicare Supplement premium increased enough that you're considering changing coverage?
Those are very different situations—and they shouldn't automatically lead to the same Medicare decision.
Medicare's 2027 Open Enrollment period runs October 15 through December 7, 2026, with changes generally becoming effective January 1, 2027. Medicare recommends beginning to compare your current coverage with 2027 options starting October 1.
Before you make a decision, here are four areas I believe deserve a careful review.
- Before Choosing Medicare Advantage, Check Your Doctors One of the easiest Medicare mistakes to make is getting excited about a plan's premium or additional benefits before looking closely at its provider network.
Start with your doctors.
Then check:
- Your primary care physician
- Specialists you currently see
- Hospitals you prefer
- Medical groups
- Prescription drugs
- Pharmacies
- Referral requirements
- Prior authorization requirements
Many Medicare Advantage plans use provider networks. Depending upon the type of plan, going outside the network may either cost more or may generally not be covered except under certain circumstances.
Medicare also explains that Medicare Advantage plans typically require prior authorization for certain services or supplies, while referral requirements differ by plan type.
This becomes particularly important if you already have established relationships with physicians.
A plan can have an attractive premium and valuable additional benefits and still be the wrong plan for you if it separates you from the doctors or facilities you want to use.
A simple rule for 2027 Don't begin with:
"What does this plan give me?"
Begin with:
"Can I receive care where and from whom I want to receive it?"
Then evaluate the benefits.
Medicare Advantage 2027: Will You Still Be Able to See Your Doctors?
2. If You're Healthy at 65+, Your Medicare Calculation May Be Different Here's a Medicare conversation that doesn't happen nearly enough.
What if you're relatively healthy?
Maybe you're already investing considerable money in staying healthy through things such as:
- Pilates
- Personal training
- Chiropractic care
- Dental care
- Vision care
- Acupuncture
- Supplements
- Concierge medicine
- Other wellness services
That's exactly the person I was speaking to in my second Medicare video.
You may look at healthcare differently from someone seeing multiple specialists every month.
That doesn't automatically mean Medicare Advantage is right for you.
It also doesn't automatically mean Medigap is right for you.
It means you should understand what you're paying for and what you're receiving in return.
For example, one of the major attractions of Original Medicare combined with Medigap can be broader provider access.
On the other hand, Medicare Advantage plans may include additional benefits beyond Original Medicare, although those benefits and their rules vary considerably between plans.
So rather than asking:
"Which Medicare option is best?"
Try asking:
"Which Medicare structure fits the way I currently live, spend and use healthcare?"
That's a much better question.
And don't make this decision solely based on how healthy you are today. Think about the financial consequences if your healthcare needs change unexpectedly.
Healthy at 65+? Medicare Advantage vs Medigap for Active Adults
3. When Does Medigap Deserve a Serious Look? Medigap—also called Medicare Supplement Insurance—is additional insurance sold by private companies that helps pay some of the healthcare costs that Original Medicare doesn't pay.
It is not a replacement for Medicare.
It works alongside Original Medicare.
There are several situations where I believe someone should at least investigate Medigap carefully.
You're turning 65 and want broad access to care Some people arrive at 65 having put off doctor visits, diagnostic work or specialist appointments.
I sometimes jokingly call this "deferred maintenance."
For someone who wants to investigate several health concerns or obtain additional opinions, provider access can become extremely important. That's one of the circumstances discussed in my third video.
You're frustrated with access under your current coverage If you frequently encounter difficulty getting referrals, seeing specialists, reaching preferred facilities or navigating your current network, that's a legitimate reason to review how you're receiving Medicare coverage.
It doesn't automatically mean changing to Medigap is appropriate.
It means something important has changed in your healthcare experience and deserves evaluation.
You anticipate greater healthcare needs Maybe surgery is on the horizon.
Perhaps rehabilitation or skilled nursing care could become important.
Or maybe a medical condition has changed.
These are exactly the moments when people often discover that access becomes more important than it seemed when they were healthy.
Charise addresses anticipated surgery, rehabilitation and skilled nursing needs specifically in her discussion of circumstances that might cause someone to reconsider their Medicare structure.
One important warning Be very careful about dropping existing Medigap coverage with the assumption that you can simply get it back later.
Medicare specifically cautions that if you drop a Medigap policy, in many circumstances you may not be able to get it back.
That's why this decision deserves more than a quick premium comparison.
3 Reasons to Consider Medigap in 2027
4. If Your Medigap Premium Is Getting Expensive, Review Before You Cancel This may be one of the biggest Medicare questions I hear:
"My Medicare Supplement premium keeps getting more expensive. What am I supposed to do?"
The worst approach is usually to make a major coverage decision out of frustration.
There may be alternatives worth reviewing first.
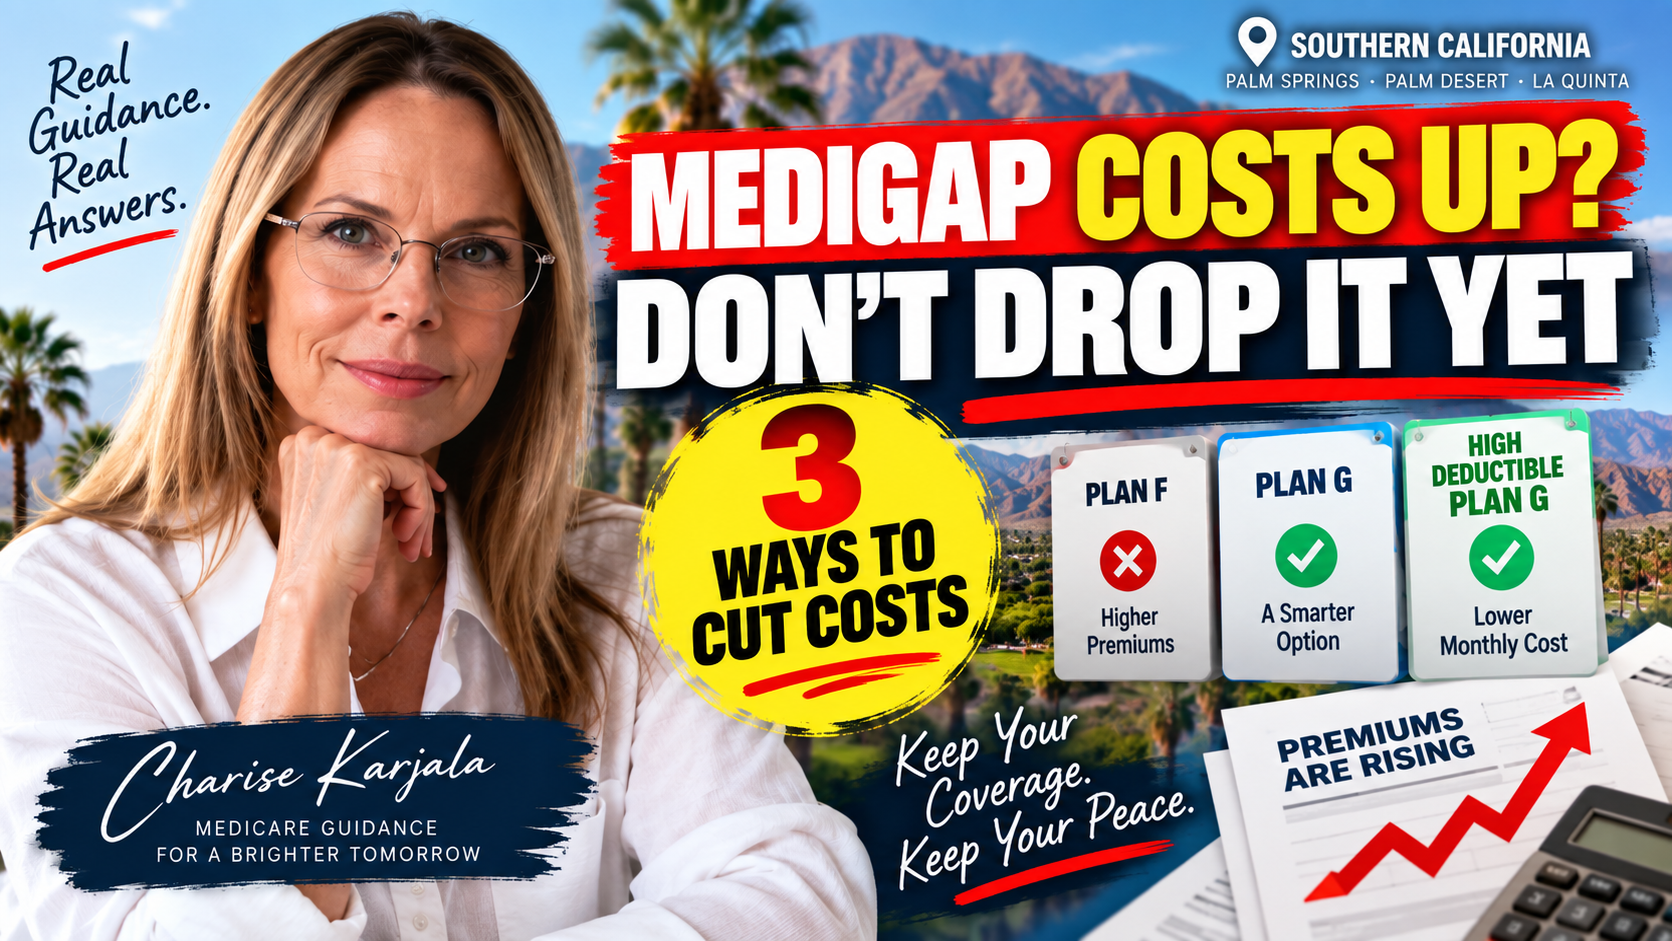
Plan F vs. Plan G If you have an older Plan F, comparing the cost with Plan G may be worthwhile.
There are important eligibility differences. People who became newly eligible for Medicare on or after January 1, 2020 generally can't buy Plan F.
But people who already have eligible older coverage may have different options.
The important point isn't that everyone should switch.
It's that the numbers deserve to be compared.
Plan G vs. Plan N Plan N can have a lower premium in some situations, but the benefits aren't identical.
Medicare's official comparison shows that Plan N may require copayments of up to $20 for certain office visits and up to $50 for certain emergency-room visits that don't result in inpatient admission. Plan N also doesn't cover Medicare Part B excess charges, while Plan G does.
That's why I don't recommend looking only at the premium.
Ask what you're giving up in exchange.
High-Deductible Plan G Another possibility for some beneficiaries is high-deductible Plan G.
Under this design, you accept greater upfront exposure in return for potentially lower premiums.
For 2026, Medicare sets the high-deductible amount for qualifying high-deductible Plans F and G at $2,950 before the policy begins paying covered costs. The 2027 amount may differ when Medicare publishes the new figure.
That distinction matters.
Someone with adequate savings who rarely uses healthcare may view that tradeoff differently from someone with frequent medical expenses and limited emergency reserves.
This is why one of my mother's favorite expressions applies surprisingly well to Medicare:
Don't become penny wise and pound foolish.
Saving money on premiums is great.
Saving $100 and accidentally assuming thousands of dollars of additional financial exposure without realizing it isn't.
Medigap Premium Too High? Ways to Reduce Medicare Supplement Costs
California Residents Have Another Medigap Opportunity to Know About Because I work with many people throughout Palm Springs, Palm Desert, La Quinta and the surrounding Coachella Valley, there's an additional California rule worth understanding.
California has what's commonly called the Medigap Birthday Rule.
If you already have Medigap insurance, the California Department of Insurance says you currently have a 60-day open-enrollment period following your birthday each year during which you can purchase another Medigap policy without medical screening or a new waiting period, provided the new policy offers the same or lesser benefits.
This is different from Medicare's fall Open Enrollment period.
That's an important distinction.
The October 15–December 7 Medicare Open Enrollment period primarily concerns Medicare Advantage and prescription drug coverage. It should not be treated as a universal Medigap switching period.
So What's the Best Medicare Plan for 2027? There isn't one answer.
And anyone trying to give every Medicare beneficiary the same answer is ignoring the most important part of the equation:
- You.
- Your health.
- Your doctors.
- Your prescriptions.
- Your finances.
- Your travel.
- Your preferred hospitals.
- Your comfort with networks.
- Your willingness to accept larger potential out-of-pocket expenses in exchange for a lower monthly premium.
And perhaps most importantly:
What happens if your health changes?
That is why I encourage people to stop looking at Medicare as something they choose once and forget forever.
Life changes.
Health changes.
Plans change.
Provider networks change.
Premiums change.
And your Medicare strategy may need to change with them.
Your 2027 Medicare Review Checklist Before making a Medicare decision this year, answer these questions:
- Are my doctors still participating?
- Are my preferred specialists and hospitals accessible?
- Are my prescriptions covered, and what will they cost?
- Do I need referrals?
- Which services require prior authorization?
- How much am I paying every month in premiums?
- What is my potential out-of-pocket exposure?
- Am I paying for broad access that I value—or rarely use?
- Would I be financially comfortable if I suddenly needed significant medical care?
- Have my healthcare needs changed during the last year?
Those questions will tell you much more than an advertisement promising another benefit.
Medicare 2027: Start With Your Life, Not the Brochure Medicare doesn't have to be reduced to a fight between Medicare Advantage and Medigap.
Both approaches can serve different people in different circumstances.
The better question is:
Which structure makes sense for the life you're actually living—and the healthcare risks you're willing and financially able to accept?
That's what these four videos are designed to help you understand.
And if you're still unsure, that's exactly what a Medicare review is for.
Schedule a 15-minute Medicare conversation with Charise Karjala
We'll look at where you are today, what's important to you, and what questions you should be asking before making your 2027 Medicare decisions.
Coverage, premiums, provider networks, additional benefits, eligibility, underwriting requirements and availability vary by plan, carrier, location and individual circumstances. Always review official plan documents and Medicare information before enrolling, disenrolling or changing coverage.