Medigap and Medicare Advantage Have Different Enrollment Rules
This is another area where people get confused.
The Medicare Annual Election Period is primarily associated with Medicare Advantage and prescription drug coverage.
Medigap works differently.
You may have guaranteed-issue rights in certain situations.
You may have state-specific protections.
You may need underwriting in other situations.
So before changing Medigap coverage, always understand:
When can I change?
Do I have guaranteed-issue rights?
Will underwriting apply?
Can I get my old coverage back if I change my mind?
Those questions matter just as much as the premium.
What About Dropping Medigap Entirely? Some people eventually ask:
“What if I just keep Original Medicare and pay the rest myself?”
That is a serious financial decision.
Original Medicare does not have the same annual out-of-pocket cap structure that Medicare Advantage plans do.
Without Medigap, you may be responsible for substantial cost sharing depending on the care you receive.
Charise’s concern in the transcript is that someone may save on premium but expose themselves to much larger expenses if a serious medical event occurs.
That is why going without supplemental protection should never be treated as a casual cost-saving move.
A Better Way to Think About the Decision Rather than asking:
“How do I get the cheapest Medigap plan?”
Ask:
“How much protection do I want to keep?”
Then:
“What is the least expensive way to get that level of protection?”
That is a very different thought process.
It starts with your risk tolerance.
Then it looks at cost.
Not the other way around.
Your Medigap Cost-Savings Checklist If your Medicare Supplement premium is getting too expensive, work through this list before making a change.
Review your current plan Which standardized Medigap plan do you have?
Compare your premium. Has the premium risen significantly?
If you have Plan F Would Plan G provide similar protection at a meaningfully lower total cost?
If you are considering Plan N How much would you really save after factoring in copays and uncovered excess charges?
Compare carriers Are you paying more than another carrier charges for the same standardized plan letter?
Consider high-deductible Plan G Could you comfortably absorb the deductible and other upfront costs?
Review your savings Do you have enough cash reserves to handle a bad healthcare year?
Check California birthday-rule options Do you have an upcoming birthday window that may give you additional flexibility?
Think about future health Would this change still feel comfortable if your healthcare needs increased next year?
Don’t Make a Permanent Decision Over a Temporary Premium Increase This is probably the most important takeaway.
If your Medigap premium has become frustrating, that is a reason to review your coverage.
It is not necessarily a reason to abandon it.
There may be ways to:
Change plan letters
Change carriers
Accept a higher deductible
Reduce premiums
Preserve meaningful protection
Better align coverage with your actual financial situation
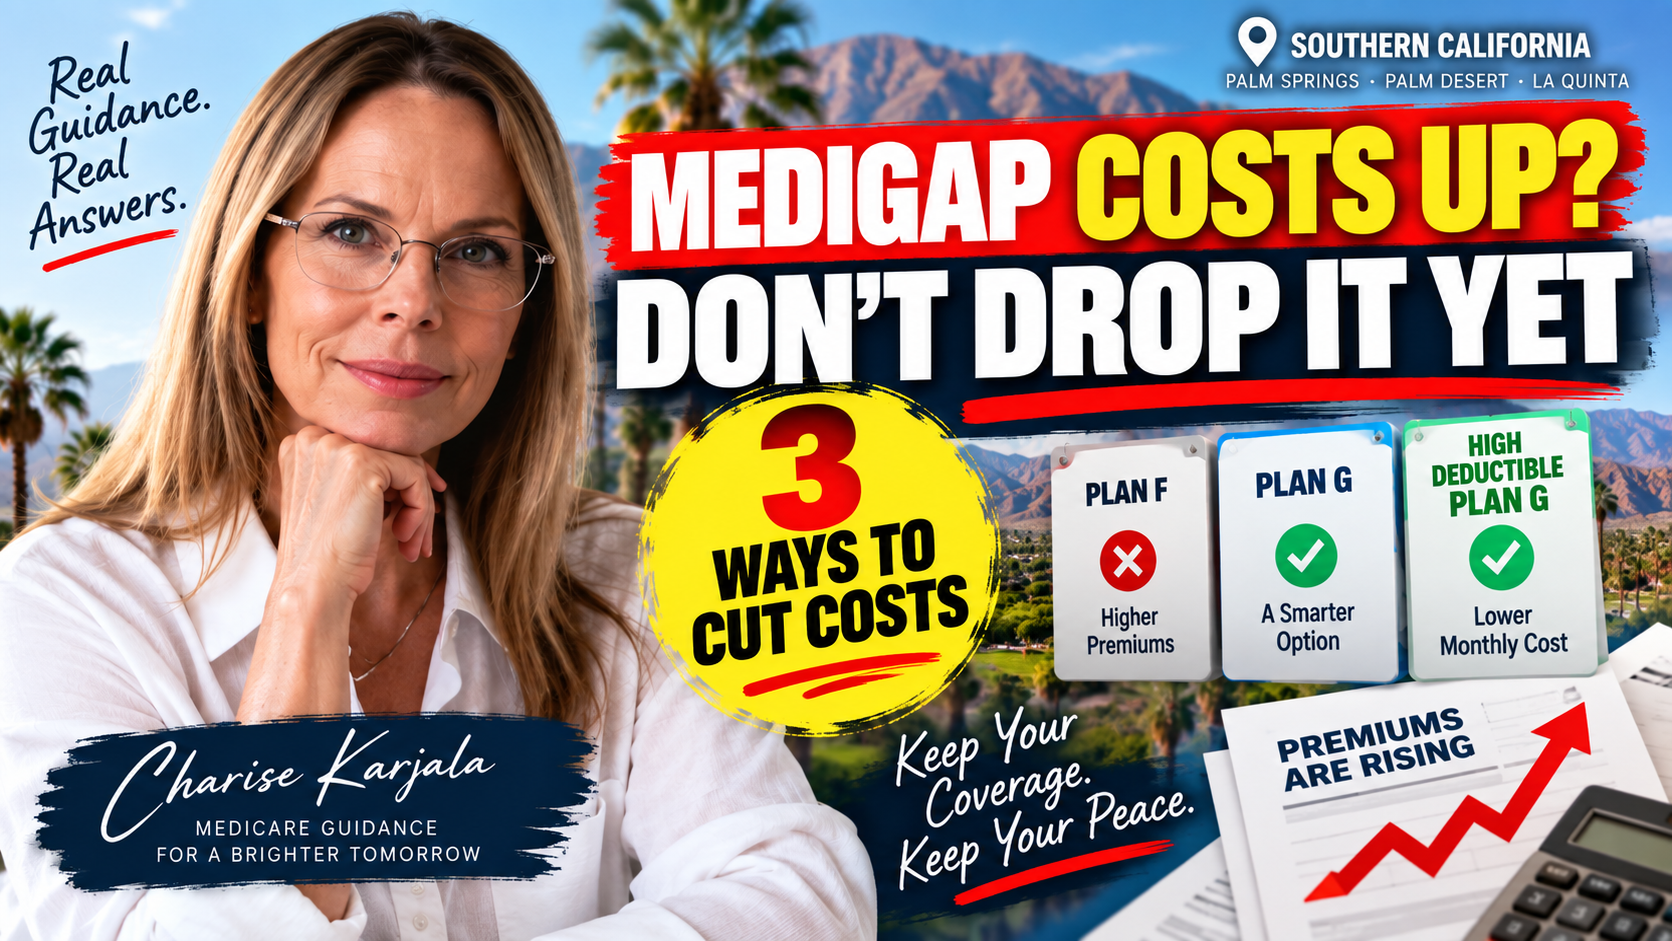
That is why Charise ends the video by encouraging people to review their choices rather than simply throwing away coverage.
Watch: What to Do When Medigap Gets Too Expensive
In this video, Charise walks through Plan F vs. Plan G, Plan G vs. Plan N, high-deductible Plan G, and the risks of eliminating Medigap coverage solely to reduce monthly premiums.
Need Help Lowering Your Medicare Supplement Costs? If your Medigap premium has jumped and you are unsure what to do next, a policy review can help.
If you are in Palm Springs, Palm Desert, La Quinta, Rancho Mirage, or elsewhere in Southern California, Charise Karjala can help you compare your current coverage with available alternatives.
Schedule a 15-Minute Medicare Conversation With Charise We can review:
Your current Medigap plan
Your monthly premium
Plan F vs. Plan G
Plan G vs. Plan N
High-deductible Plan G
California birthday-rule opportunities
Your health needs
Your financial comfort level
The goal is not simply to find the cheapest plan.
It is to find the right balance between cost, protection, and peace of mind.
← 3 Reasons to Consider Medigap in 2027
← Complete 2027 Medicare Guide
← Medicare Advantage vs. Medigap for Healthy Adults
Medigap premiums, underwriting rules, guaranteed-issue rights, plan availability, and state protections vary. Review official Medicare information and applicable California rules before changing or dropping coverage.