What Should I Compare During Medicare Annual Enrollment Besides the Monthly Premium?
Why Your Monthly Premium Is Only Part of the Medicare Cost Picture
he monthly premium is important—but it is only one part of evaluating Medicare coverage.
During Medicare Annual Enrollment, people understandably want to know:
“How much is the premium?”
That's an important question. It shouldn't be the only one.
“A low Medicare premium doesn't necessarily mean low health-care costs.” — Charise Karjala
When I review Medicare coverage with someone, I want to understand both what the coverage costs to maintain and what it could cost when that person actually needs medical care.
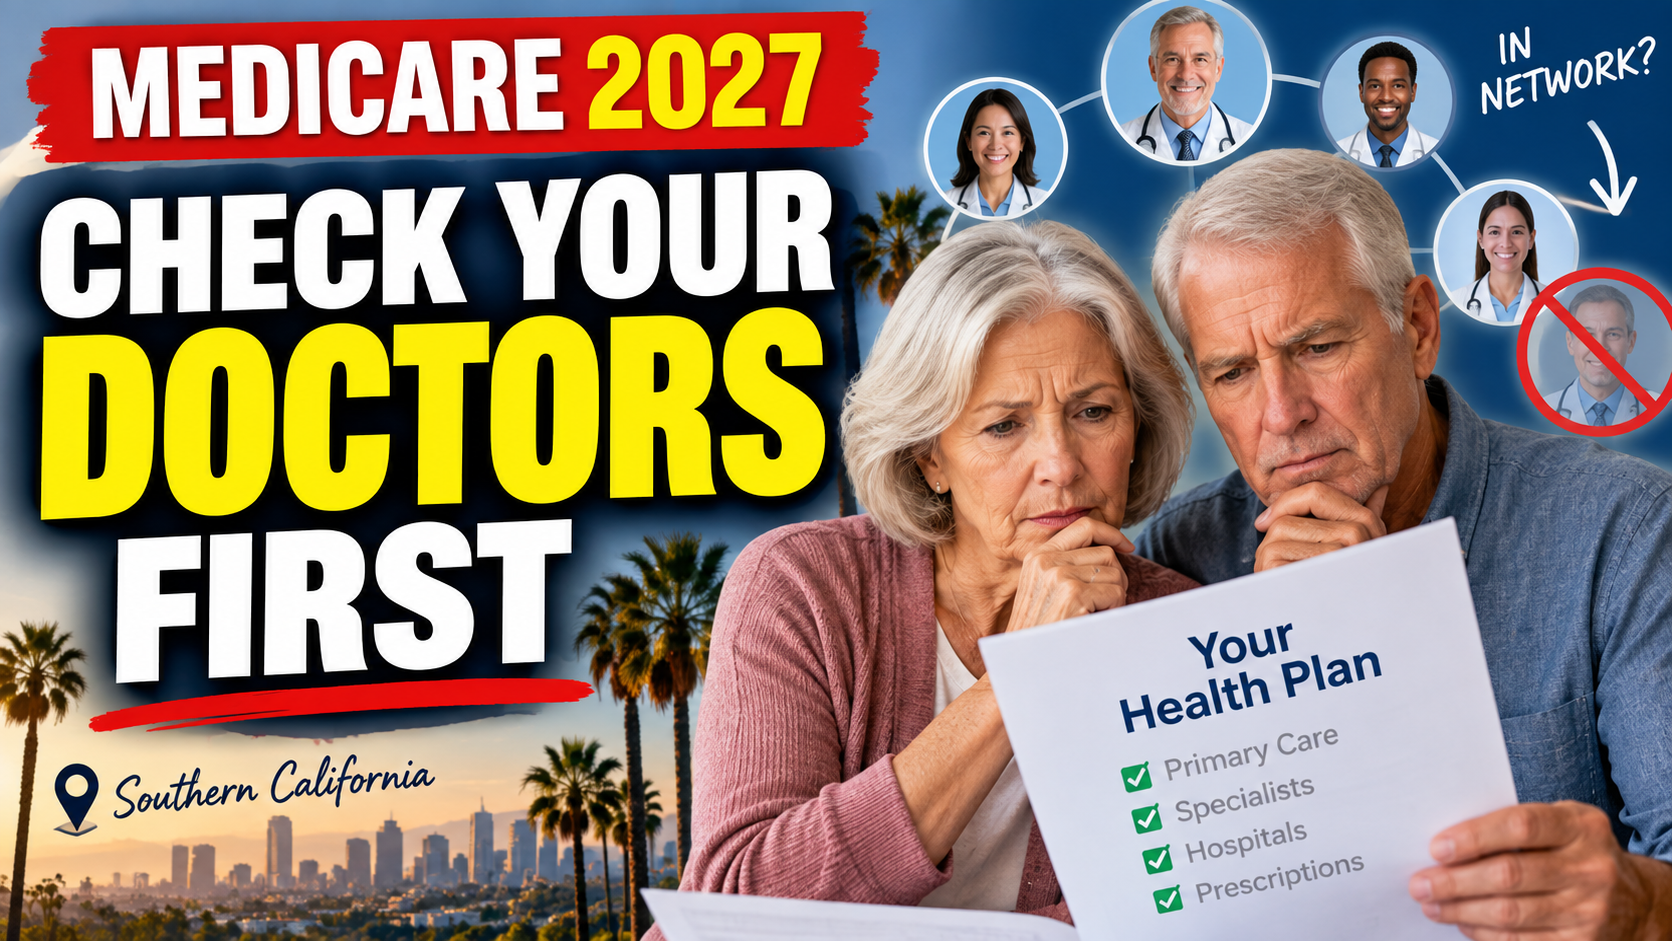
1. Review Your Doctors and Hospitals
Start with the health-care providers that matter to you.
Check your primary care physician, specialists, preferred hospitals and health systems.
Provider networks can change. If maintaining access to particular providers is important to you, verify their participation rather than assuming that last year's situation will automatically continue.
2. Review Your Prescription Drugs
Bring your current medication list to your annual Medicare review.
Look at whether your medications are covered, their formulary tiers, pharmacy options, potential restrictions and expected costs.
A plan that appears inexpensive based on its premium can look very different after prescription expenses are considered.
3. Review Your Total Financial Exposure
This is where I encourage people to look much deeper than the monthly premium.
Consider deductibles, copays, coinsurance, hospital expenses, outpatient services, diagnostic testing and other potential costs.
If you're evaluating Medicare Advantage coverage, also look carefully at the plan's maximum out-of-pocket limit for covered Part A and Part B services.
Maximum out-of-pocket amounts vary among plans and can change from year to year.
“Your maximum out-of-pocket amount isn't a footnote. It's part of your financial planning.” — Charise Karjala
That's why I frequently tell clients:
“Don't just ask what your Medicare plan costs to own. Ask what it could cost you to use.” — Charise Karjala
A $0 or low-premium Medicare Advantage plan may still be appropriate for someone. The important thing is understanding the potential financial exposure along with the premium.
4. Review Whether Your Coverage Still Fits Your Life
Your health-care needs aren't frozen in time.
Have your medications changed?
Are you seeing new specialists?
Are you traveling more?
Has your budget changed?
Has something happened with your health that makes you think differently about how you want to receive care?
Your Medicare coverage should make sense for your circumstances today.
And sometimes an annual review produces a very simple answer:
Your existing coverage still fits you well.
“A Medicare plan review isn't about changing plans. It's about knowing whether you should stay or change.” — Charise Karjala
The Charise 4-Point Medicare Review
I encourage Medicare beneficiaries to evaluate four things each year:
Doctors. Prescriptions. Financial exposure. Your life.
Or, put another way:
“Every annual Medicare review should answer four questions: Are my doctors accessible? Are my prescriptions covered appropriately? What is my total financial exposure? And does this coverage still fit my life?” — Charise Karjala
After more than 20 years working in insurance, I've learned that focusing only on premium can give you an incomplete picture.
The question I want people to consider is:
“What will my health-care strategy look like when I actually need to use it?” — Charise Karjala
Understand the coverage. Understand the potential costs. Ask questions. Then make an informed decision.
About Charise Karjala
Charise Karjala is a HealthMarkets Insurance Agent with more than 20 years of insurance experience, helping individuals understand Medicare and health insurance options throughout Southern California, Arizona and Nevada.
Educational information only. Medicare plan premiums, benefits, provider networks, formularies, cost sharing, maximum out-of-pocket limits and availability vary by plan and location and may change from year to year. Review official plan information before making enrollment decisions.