Medicare Advantage 2027: Will You Still Be Able to See Your Doctors?
Medicare Advantage 2027: Will Your Doctors Still Be In Network?
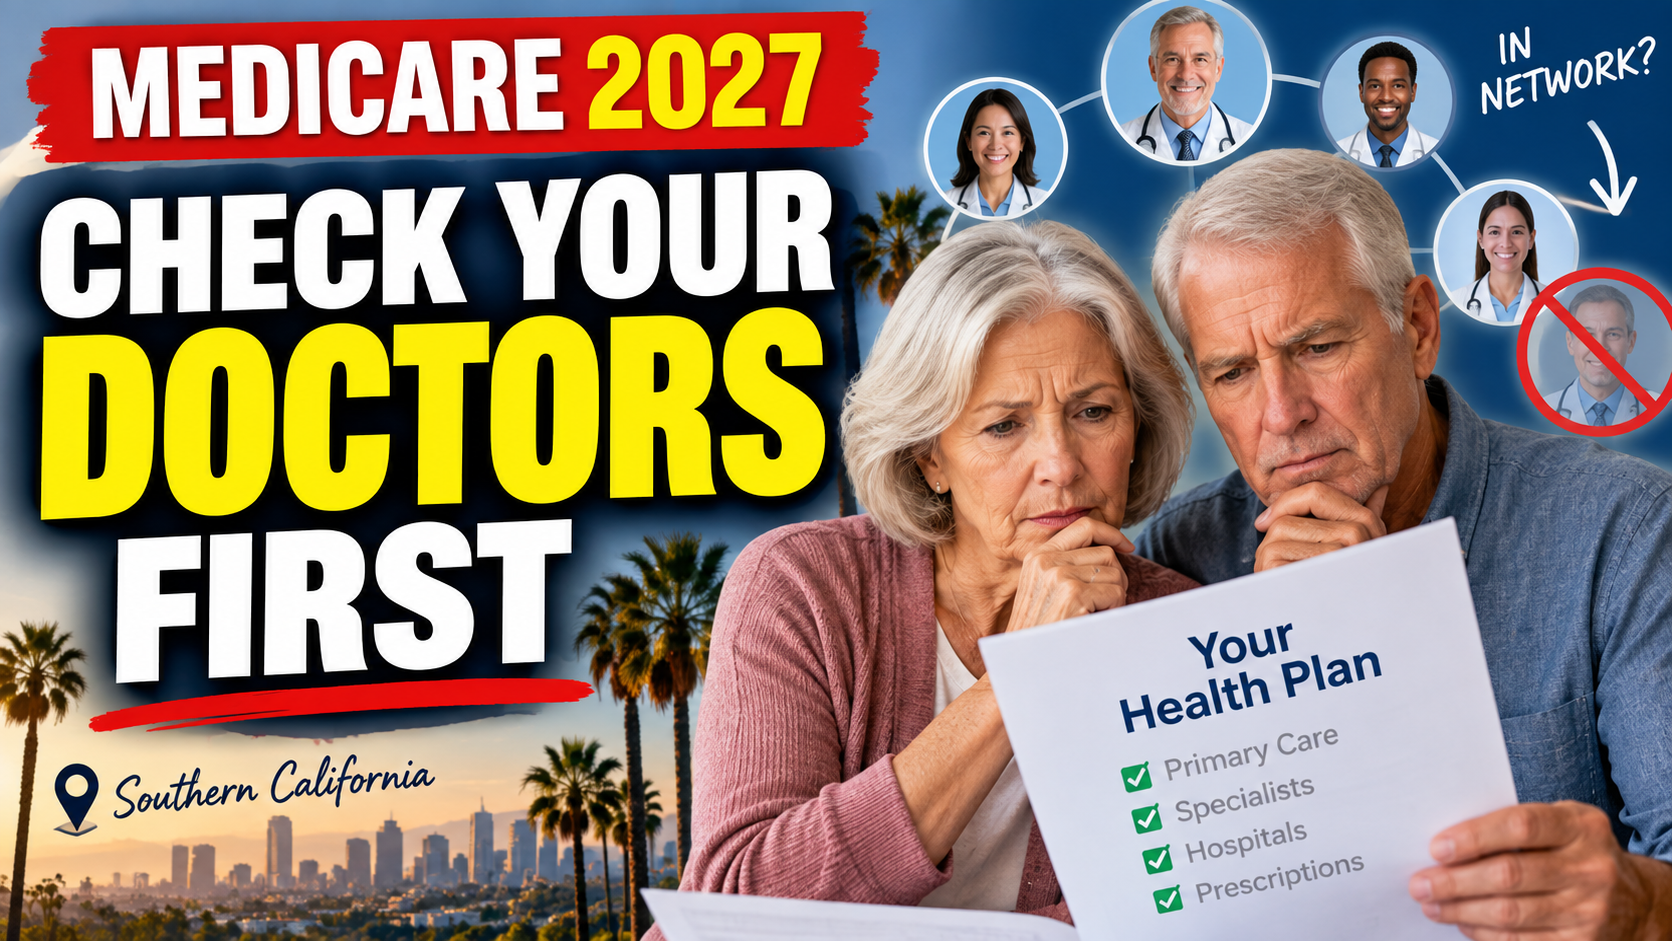
Medicare Advantage 2027: Before You Choose a Plan, Check Your Doctors Medicare Annual Enrollment is approaching, and if you’re considering Medicare Advantage for 2027, you're probably going to see plenty of advertising.
You may hear about:
- Lower premiums
- Dental benefits
- Vision coverage
- Prescription drug benefits
- Fitness programs
- Over-the-counter allowances
- Giveback benefits
- Other extras
Those benefits may be valuable.
But I want you to check something else before you become excited about any of them:
Can you still see the doctors you want to see? That simple question can have a major effect on whether a Medicare Advantage plan actually works for you.
Medicare's annual Open Enrollment period runs from October 15 through December 7, and changes generally take effect January 1. Medicare specifically recommends reviewing your current plan's costs and benefits and comparing options for the coming year.
So before choosing coverage for 2027, here is what I believe you should know.
Medicare Advantage Plans Can Have Provider Networks One of the most important differences between Original Medicare and many Medicare Advantage plans is how you access doctors and hospitals.
With Original Medicare, you can generally use any doctor or hospital in the United States that accepts Medicare.
With Medicare Advantage, you may need to use doctors, hospitals and other providers within your plan's network for non-emergency care. Some plans provide out-of-network benefits, but you may pay more.
That means two Medicare Advantage plans that look similar on paper can create very different healthcare experiences.
One could include:
Your primary care doctor.
Another may not.
One could include:
The cardiologist you've seen for six years.
Another may use a completely different medical group.
One could include:
The hospital you prefer.
Another may direct you somewhere else.
That doesn't automatically make one plan good and another bad.
It means the network has to fit you.
Start With the Doctors You Already Have Before comparing additional benefits, write down the healthcare providers who matter to you.
I would include:
Your primary care physician Don't simply search the doctor's name and assume you're finished.
Verify that the physician participates in the specific plan you're considering for 2027.
Your specialists If you regularly see a:
Cardiologist
Oncologist
Neurologist
Pulmonologist
Orthopedic specialist
Endocrinologist
Dermatologist
Ophthalmologist
Other specialist
check each one
This becomes particularly important if you are already receiving treatment for an ongoing medical condition.
Your preferred hospitals Ask yourself:
If something serious happened tomorrow, where would I want to receive care?
Then verify whether that hospital participates in the plan.
CMS requires applicable Medicare Advantage organizations to maintain provider networks sufficient to provide adequate access to covered services, but each plan's actual contracted network can still differ.
That distinction matters.
A plan can satisfy Medicare's network requirements and still not include your preferred physician or hospital.
HMO and PPO Medicare Advantage Plans Work Differently Not every Medicare Advantage plan uses its network in exactly the same way.
This is where a lot of confusion occurs.
Medicare Advantage HMO With an HMO, Medicare says you generally must receive care from providers and facilities within the plan's network, except for situations such as emergency care, urgent care and out-of-area dialysis.
HMOs also generally require a referral before seeing a specialist.
Medicare Advantage PPO A PPO also has a provider network.
However, you can generally receive covered services outside the network, although your costs may be higher.
Medicare says PPO members generally don't need referrals to see specialists.
That difference can become extremely important.
A person who values maximum flexibility may view these arrangements very differently from someone who is comfortable receiving nearly all of their care within one coordinated medical system.
Don't Check Only Your Primary Doctor This is one of the mistakes I see people make.
They ask:
"Is Dr. Smith in the plan?"
The answer is yes.
And they stop investigating.
But your primary physician is only one piece of your healthcare system.
Think several steps beyond that doctor.
If your primary physician discovers something concerning:
- Where can they send you?
- Which specialists are available?
- Which imaging centers?
- Which surgical groups?
- Which hospitals?
- Which rehabilitation facilities?
- Which medical groups?
You don't necessarily need every famous physician in Southern California available to you.
But you should understand the healthcare system you're entering.
Ask About Specialist Referrals Another question that deserves attention is:
Will I need a referral to see a specialist? The answer depends on the type of Medicare Advantage plan.
As noted above, HMOs generally require referrals for specialists, while PPOs generally don't. Special Needs Plans can differ depending upon whether they operate as HMOs or PPOs.
For some people, that isn't a problem at all.
They appreciate having a primary physician coordinate their care.
Other people want to be able to make an appointment directly with a specialist.
Neither preference is inherently correct.
What matters is knowing which system you're choosing before you need it.
Understand Prior Authorization Before You Enroll Provider networks aren't the only issue.
You should also understand prior authorization.
Prior authorization means the health plan may require approval before certain services, procedures or medical supplies are covered.
Medicare says people in Medicare Advantage will typically need prior authorization for certain services or supplies.
Examples can vary by plan.
That's why I would ask:
Which services require prior authorization under this plan?
And:
How does the authorization process work?
Don't wait until you're trying to schedule a procedure to learn the answer.
CMS has continued implementing rules and reporting requirements designed to make Medicare Advantage prior authorization processes more transparent and efficient.
But prior authorization remains an important difference to understand when comparing Medicare Advantage with Original Medicare.
What About Special Needs Plans? This was one of the subjects I discussed in my video.
Special Needs Plans, usually called SNPs, are Medicare Advantage plans designed for people with certain characteristics or healthcare needs.
Some SNPs operate as HMOs.
Others operate as PPOs.
Medicare says that if a SNP is an HMO, members generally must obtain care within the plan's network, except for certain exceptions such as emergency or urgent care. PPO SNPs can provide Medicare-covered services outside the network.
SNPs can offer important care coordination and benefits for eligible beneficiaries.
But again, the same principle applies:
Understand the network before enrolling. If you have a chronic condition and already have physicians you trust, don't assume those providers are part of the plan.
Verify.
A Small Extra Benefit Shouldn't Distract You From a Big Healthcare Question Suppose one plan offers you an additional monthly benefit.
That's attractive.
Everyone likes saving money.
But imagine that receiving that benefit requires moving from a healthcare system containing several physicians you know and trust into a much smaller network.
Would you still make the change?
Maybe.
Maybe not.
But that's the calculation you should consciously make.
This is one of the central ideas in my original video: don't let a comparatively small financial benefit distract you from understanding what may be changing in your access to physicians and specialists.
Ask What Happens If Your Health Changes Here's another question I wish more people asked when choosing Medicare coverage:
What if I'm healthy today—but not six months from now? When you're healthy, provider access can feel theoretical.
You may visit your primary doctor once or twice a year.
Maybe that's it.
Then something unexpected happens.
A heart issue.
Cancer.
An orthopedic problem.
A neurological concern.
Suddenly, the specialists and medical facilities available to you become much more important.
That doesn't mean you should automatically avoid Medicare Advantage.
It means you should evaluate the plan not only for the healthcare you're receiving today, but for reasonable situations you might encounter during the coming year.
Your 2027 Medicare Advantage Doctor Checklist Before joining or switching Medicare Advantage plans, take a few minutes and work through this checklist.
Primary Care Is my primary physician in this specific 2027 plan?
Specialists Are the specialists I already use included?
Hospitals Are my preferred hospitals participating?
Medical Group Am I comfortable with the medical group or healthcare system associated with the plan?
Referrals Will I need referrals before seeing specialists?
Prior Authorization Which services or procedures require plan approval?
Prescriptions Are my medications on the plan's formulary, and what will they cost?
Pharmacy Are my preferred pharmacies included, and are they preferred-cost pharmacies?
Travel What happens if I need non-emergency care while away from Southern California?
Changing Health Needs Would I still be comfortable with this network if my health changed significantly next year?
If you can't answer those questions, you aren't ready to choose the plan yet.
Medicare Advantage Isn't Just About Benefits. It's About Access. This is the point I want people to remember.
A Medicare Advantage plan isn't simply a collection of benefits.
It's also a healthcare delivery system.
The network matters.
The specialists matter.
The hospitals matter.
Referral rules matter.
Prior authorization matters.
And how much those things matter depends upon you.
Medicare itself highlights doctor and hospital choice, referrals and prior authorization when comparing Original Medicare with Medicare Advantage.
So when you compare plans for 2027, don't begin with:
"Which plan gives me the most stuff?"
Begin with:
"How will I actually receive healthcare under this plan?"
That's the question that can prevent unpleasant surprises later.
In the accompanying video, I discuss why I believe provider access deserves particularly close attention this enrollment season and why beneficiaries should understand the healthcare network behind a plan—not simply the benefits advertised in front of it.
Need Help Reviewing Your 2027 Medicare Options? Medicare can become confusing very quickly when you're comparing premiums, providers, networks, prescription coverage and additional benefits at the same time.
You don't have to figure it out from an advertisement.
If you're in Palm Springs, Palm Desert, La Quinta or elsewhere in Southern California, I'm happy to help you look at the questions that matter for your individual situation.
Schedule a 15-Minute Medicare Conversation With Charise Karjala We'll look at your current coverage, your physicians, your priorities and the questions you should ask before making a change.
Continue the 2027 Medicare Guide ← Complete 2027 Medicare Guide: Four Decisions to Review Before Open Enrollment
Next → Healthy at 65+? Medicare Advantage vs Medigap for Active Adults
Medicare plan benefits, provider networks, drug formularies, costs and availability vary by plan and location and may change from year to year. Always verify information with the plan and official Medicare resources before enrolling or changing coverage.